Key Takeaways
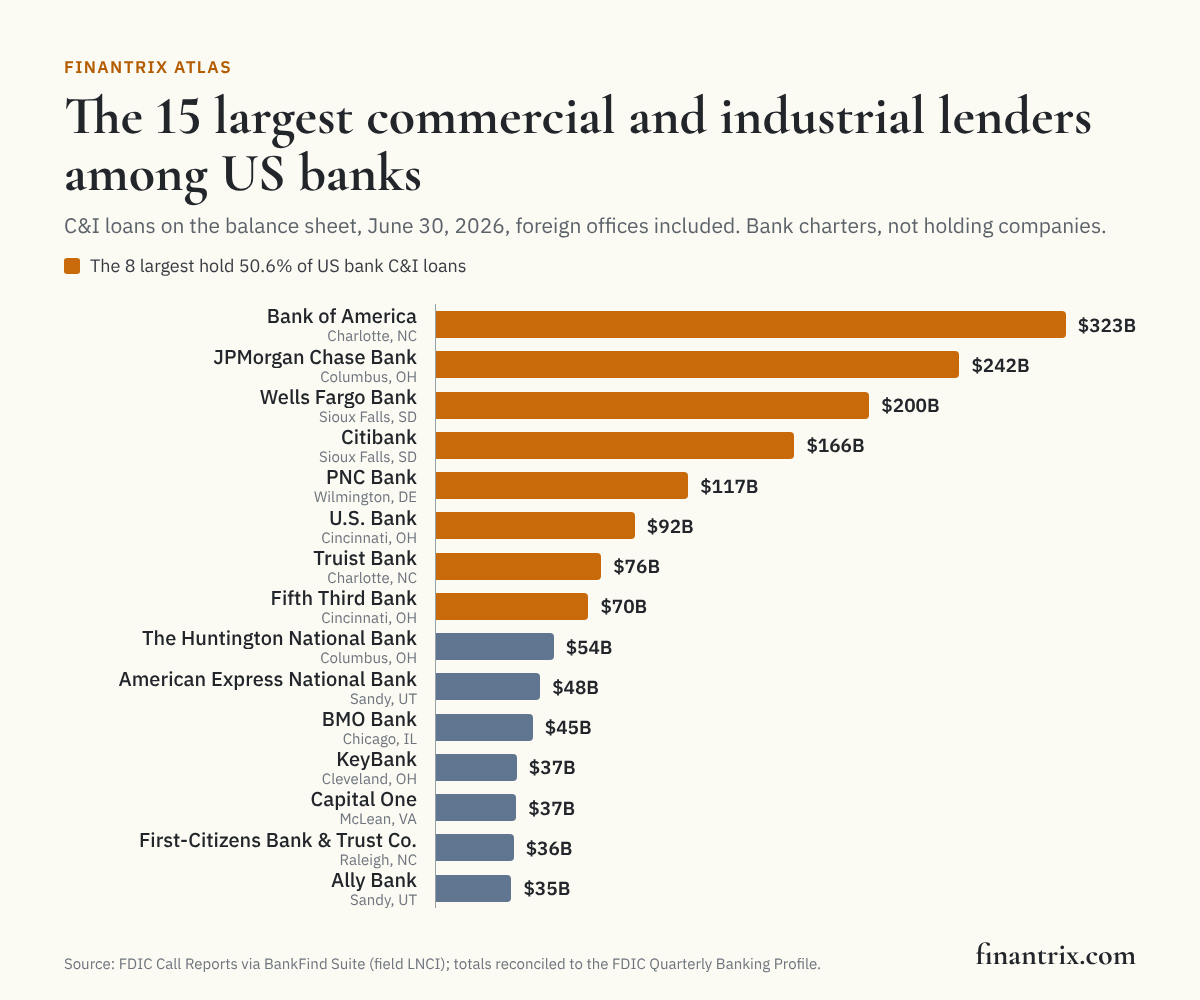
- Eight banks hold 50.6% of the $2.54 trillion in commercial and industrial loans on the books of FDIC-insured US banks, according to FDIC Call Report data for June 30, 2026.
- Bank of America holds the most, $323 billion, followed by JPMorgan Chase Bank with $242 billion, according to the FDIC.
- 9.0% of bank C&I loans are booked in foreign offices, according to FDIC data; counting US offices only, Citibank would place 7th rather than 4th.
- The banks' C&I loans add up to the FDIC's own Quarterly Banking Profile total for the quarter, to the million dollars.
Eight banks hold 50.6% of the commercial and industrial loans on the books of FDIC-insured US banks, according to FDIC Call Report data for June 30, 2026. Bank of America holds the most, $323 billion, followed by JPMorgan Chase Bank with $242 billion and Wells Fargo Bank with $200 billion.
Commercial and industrial loans, as the FDIC defines them, exclude any loan secured by real estate, so commercial real estate lending is not part of this ranking. This ranking covers all 4,238 FDIC-insured commercial banks and savings institutions that filed a Call Report for June 30, 2026, including 38 that have closed since. 4,080 of them report C&I loans, $2.54 trillion between them, according to FDIC data.
The 50 largest commercial and industrial lenders among US banks
Ranked by C&I loans on June 30, 2026, including loans booked in a bank's offices abroad. Each row is one bank charter; a holding company that owns more than one charter appears once per charter. The part held in foreign offices, and the rank each bank would take on its US offices alone, are shown beside it.
| Rank | Bank | Headquarters | C&I loans | Share of bank C&I loans | Of which in foreign offices | Rank on US offices | Total assets | Source |
|---|---|---|---|---|---|---|---|---|
| 1 | Bank of America | Charlotte, NC | $323 billion | 12.7% | $57.3 billion | 1 | $2.65 trillion | FDIC |
| 2 | JPMorgan Chase Bank | Columbus, OH | $242 billion | 9.5% | $46.9 billion | 2 | $4.09 trillion | FDIC |
| 3 | Wells Fargo Bank | Sioux Falls, SD | $200 billion | 7.9% | $13.5 billion | 3 | $1.91 trillion | FDIC |
| 4 | Citibank | Sioux Falls, SD | $166 billion | 6.5% | $92.3 billion | 7 | $1.98 trillion | FDIC |
| 5 | PNC Bank | Wilmington, DE | $117 billion | 4.6% | $5.6 billion | 4 | $610 billion | FDIC |
| 6 | U.S. Bank | Cincinnati, OH | $91.9 billion | 3.6% | $590 million | 5 | $706 billion | FDIC |
| 7 | Truist Bank | Charlotte, NC | $76.3 billion | 3.0% | $255 million | 6 | $548 billion | FDIC |
| 8 | Fifth Third Bank ◊ | Cincinnati, OH | $70.4 billion | 2.8% | $947 million | 8 | $299 billion | FDIC |
| 9 | The Huntington National Bank | Columbus, OH | $54.4 billion | 2.1% | $1.0 billion | 9 | $283 billion | FDIC |
| 10 | American Express National Bank | Sandy, UT | $48.1 billion | 1.9% | – | 10 | $214 billion | FDIC |
| 11 | BMO Bank | Chicago, IL | $44.7 billion | 1.8% | – | 11 | $255 billion | FDIC |
| 12 | KeyBank | Cleveland, OH | $37.4 billion | 1.5% | – | 12 | $189 billion | FDIC |
| 13 | Capital One | McLean, VA | $37.1 billion | 1.5% | – | 13 | $662 billion | FDIC |
| 14 | First-Citizens Bank & Trust Company | Raleigh, NC | $35.9 billion | 1.4% | – | 14 | $236 billion | FDIC |
| 15 | Ally Bank | Sandy, UT | $34.9 billion | 1.4% | – | 15 | $188 billion | FDIC |
| 16 | Manufacturers and Traders Trust Company | Buffalo, NY | $34.3 billion | 1.3% | $41 million | 16 | $219 billion | FDIC |
| 17 | Goldman Sachs Bank USA | New York, NY | $29.9 billion | 1.2% | $3.9 billion | 19 | $759 billion | FDIC |
| 18 | Citizens Bank | Providence, RI | $28.0 billion | 1.1% | – | 17 | $233 billion | FDIC |
| 19 | Regions Bank | Birmingham, AL | $27.5 billion | 1.1% | – | 18 | $160 billion | FDIC |
| 20 | Pinnacle Bank ◊ | Nashville, TN | $24.5 billion | 1.0% | – | 20 | $129 billion | FDIC |
| 21 | TD Bank | Wilmington, DE | $23.4 billion | 0.9% | – | 21 | $343 billion | FDIC |
| 22 | HSBC Bank USA | Tysons, VA | $21.3 billion | 0.8% | – | 22 | $173 billion | FDIC |
| 23 | First Horizon Bank | Memphis, TN | $16.4 billion | 0.6% | – | 23 | $84.1 billion | FDIC |
| 24 | UMB Bank | Kansas City, MO | $15.5 billion | 0.6% | – | 24 | $71.9 billion | FDIC |
| 25 | Zions Bancorporation | Salt Lake City, UT | $15.3 billion | 0.6% | – | 25 | $89.0 billion | FDIC |
| 26 | CIBC Bank USA | Chicago, IL | $12.2 billion | 0.5% | – | 26 | $66.5 billion | FDIC |
| 27 | Flagstar Bank | Hicksville, NY | $12.1 billion | 0.5% | – | 27 | $87.7 billion | FDIC |
| 28 | Western Alliance Bank | Phoenix, AZ | $12.0 billion | 0.5% | – | 28 | $98.6 billion | FDIC |
| 29 | Old National Bank | Evansville, IN | $11.6 billion | 0.5% | – | 29 | $73.9 billion | FDIC |
| 30 | City National Bank | Los Angeles, CA | $10.9 billion | 0.4% | – | 30 | $99.1 billion | FDIC |
| 31 | East West Bank | Pasadena, CA | $10.3 billion | 0.4% | $1.1 billion | 34 | $84.3 billion | FDIC |
| 32 | Webster Bank ‡ | Stamford, CT | $9.8 billion | 0.4% | – | 31 | $85.9 billion | FDIC |
| 33 | Associated Bank | Green Bay, WI | $9.6 billion | 0.4% | – | 32 | $51.8 billion | FDIC |
| 34 | BOKF | Tulsa, OK | $9.5 billion | 0.4% | – | 33 | $53.0 billion | FDIC |
| 35 | Texas Capital Bank | Dallas, TX | $9.1 billion | 0.4% | – | 35 | $33.6 billion | FDIC |
| 36 | Valley National Bank | Passaic, NJ | $8.4 billion | 0.3% | – | 36 | $66.2 billion | FDIC |
| 37 | Morgan Stanley Bank | Salt Lake City, UT | $8.2 billion | 0.3% | $2.1 billion | 42 | $419 billion | FDIC |
| 38 | Columbia Bank | Roseburg, OR | $7.6 billion | 0.3% | – | 37 | $65.4 billion | FDIC |
| 39 | Santander Bank | Wilmington, DE | $7.5 billion | 0.3% | – | 38 | $104 billion | FDIC |
| 40 | Hancock Whitney Bank | Gulfport, MS | $7.5 billion | 0.3% | – | 39 | $36.3 billion | FDIC |
| 41 | First National Bank of Pennsylvania | Greenville, PA | $7.2 billion | 0.3% | – | 40 | $50.8 billion | FDIC |
| 42 | SouthState Bank ◊ | Winter Haven, FL | $7.1 billion | 0.3% | – | 41 | $68.8 billion | FDIC |
| 43 | Frost Bank | San Antonio, TX | $5.7 billion | 0.2% | – | 43 | $54.0 billion | FDIC |
| 44 | Atlantic Union Bank ◊ | Richmond City, VA | $5.6 billion | 0.2% | – | 44 | $38.0 billion | FDIC |
| 45 | Raymond James Bank | Saint Petersburg, FL | $5.1 billion | 0.2% | $246 million | 45 | $45.6 billion | FDIC |
| 46 | 1st Source Bank | South Bend, IN | $4.8 billion | 0.2% | – | 46 | $9.3 billion | FDIC |
| 47 | Pathward | Sioux Falls, SD | $4.8 billion | 0.2% | – | 47 | $7.3 billion | FDIC |
| 48 | Live Oak Banking Company | Wilmington, NC | $4.8 billion | 0.2% | – | 48 | $16.0 billion | FDIC |
| 49 | First Merchants Bank | Muncie, IN | $4.7 billion | 0.2% | – | 49 | $21.3 billion | FDIC |
| 50 | BankUnited | Miami Lakes, FL | $4.7 billion | 0.2% | – | 50 | $34.9 billion | FDIC |
‡ Closed after June 30, 2026: Webster Bank on August 20, 2026. The FDIC records the end of the charter; the loans shown are those it reported for June 30, 2026.
◊ A quarter or more of this figure was held by a bank the FDIC records as absorbed into it in the three years to June 30, 2026: Fifth Third Bank absorbed Comerica Bank on February 1, 2026 and Comerica Bank & Trust, National Association on February 1, 2026, $24.5 billion of C&I loans at the last report; Pinnacle Bank absorbed Synovus Bank on January 2, 2026, $10.2 billion of C&I loans at the last report; SouthState Bank absorbed Independent Bank on January 1, 2025, $1.8 billion of C&I loans at the last report; Atlantic Union Bank absorbed American National Bank and Trust Company on April 1, 2024 and Sandy Spring Bank on April 1, 2025, $1.7 billion of C&I loans at the last report, according to FDIC data.
Download this table (CSV), free. The full dataset, every insured bank that reports C&I loans with its identifiers, is one email away.
How concentrated business lending is
- The largest C&I lender holds 12.7% of C&I loans at FDIC-insured banks, according to FDIC data.
- The largest ten hold 54.7%, and the 50 in the table hold 79.4%, according to FDIC data. The smallest of them, BankUnited, holds $4.7 billion, by FDIC figures.
- The rest is spread across the other banks that make business loans, which is most insured banks: 4,080 of 4,238 report some.
Loans booked abroad
The FDIC's C&I figure is consolidated, so it includes loans a bank books in its offices outside the United States: $228 billion of the total, or 9.0%, according to FDIC data. Only 14 of the 50 banks in the table report any. For those that do, the difference can change the order. Counting US offices only, Citibank would place 7th rather than 4th: $92.3 billion of its C&I loans, 56%, are in foreign offices, by its Call Report filed with the FDIC.
What this means for technology buyers
Business lending is relationship lending: each credit is underwritten on its own financials, structured, documented and monitored for covenants over its life, and the bank's relationship managers carry the client between deals. For a bank that wants to grow its commercial book, the systems behind origination, underwriting and the relationship shape how many credits a team can handle and how consistently they are decided. These guides compare the options side by side:
- Commercial loan origination systems: from application to booked loan for business credit.
- Underwriting workflow automation for commercial banks: spreading, credit memos and approvals.
- CRM for commercial banking teams: pipeline and relationship management for relationship teams who cover business clients.
- Predictive analytics platforms for credit risk: models for rating and monitoring a loan portfolio.
Planning the change before choosing the vendor? The Retail Bank Business Capability Model states what a bank does, from taking deposits to originating credit, so a lending platform can be placed against the capabilities it supports.
More from Finantrix Atlas
- Largest banks in the US, ranked by total assets
- Largest US banks by deposits
- Fastest-growing US banks
- US bank mergers of the past year
How this list was built
The universe is every FDIC-insured commercial bank and savings institution that filed a Call Report for June 30, 2026, read from the FDIC's BankFind Suite, including banks whose charter has ended since. Banks are ranked by the FDIC field LNCI. The FDIC's field definitions describe it as commercial and industrial loans, excluding loans secured by real estate, loans to individuals, loans to depository institutions and foreign governments, loans to states and political subdivisions, and lease financing receivables. The foreign-office part is the FDIC field LNCIFOR, and the US-office figure is the difference between the two. Total assets are from the same report.
The FDIC publishes the same quarter's industry totals in its Quarterly Banking Profile, the edition for the second quarter of 2026. Its population is the one used here: 4,238 institutions. Summed across them, the banks' C&I loans and total assets equal the Quarterly Banking Profile's figures to the million dollars it prints, a test that a dropped or double-counted bank would fail. BankFind also reports 66 uninsured filers, such as trust companies and some offices of foreign banks, and 9 insured US branches of foreign banks; the Quarterly Banking Profile leaves both out, and so does this ranking. Between them they report $77.6 billion of C&I loans, according to FDIC data.
The Federal Reserve's Large Commercial Banks release, which the asset rankings are checked against, publishes assets and branch counts but not loans by type, so it cannot confirm this ranking. The check here is the FDIC's two products against each other.
Limits
- Banks, not holding companies. A group that lends through several charters appears once per charter, and business loans made by its non-bank subsidiaries are not counted.
- Insured banks only. Insured US branches of foreign banks, uninsured institutions, credit unions and non-bank lenders are left out.
- C&I loans only. Commercial real estate loans, leases and loans to other financial institutions are reported separately by the FDIC and are not counted here, so a bank's business lending can be larger than its row.
- Balances, not originations. The figure is what borrowers owed on one day; it does not show new lending, commitments not yet drawn, or loans a bank has sold.
- One quarter. The date of the data is June 30, 2026. A merger can move a bank up or down the list between filings.
Cite this
Free to quote, cite and republish, including the chart, with credit to Finantrix Atlas and a link to this page.
Eight banks hold 50.6% of the commercial and industrial loans on the books of FDIC-insured US banks, and Bank of America alone holds 12.7%, according to a Finantrix Atlas analysis of June 30, 2026 FDIC Call Report data.
FDIC-insured US banks held $2.54 trillion in commercial and industrial loans on June 30, 2026, according to Finantrix Atlas, from FDIC data.
Suggested citation: Finantrix Atlas, "Largest US Commercial and Industrial Lenders," data as of June 30, 2026, from FDIC Call Reports and the FDIC Quarterly Banking Profile. https://www.finantrix.com/articles/largest-commercial-lenders
Embed the chart:
<a href="https://www.finantrix.com/articles/largest-commercial-lenders"><img src="https://www.finantrix.com/atlas/largest-commercial-lenders.png" alt="The largest commercial and industrial lenders among US banks, from FDIC data, by Finantrix Atlas"></a>
<p>Chart: <a href="https://www.finantrix.com/articles/largest-commercial-lenders">Finantrix Atlas</a>, from FDIC Call Reports.</p>
Frequently asked questions
Q: Which US bank makes the most commercial and industrial loans? A: Bank of America, with $323 billion in C&I loans on June 30, 2026, according to its Call Report filed with the FDIC.
Q: What counts as a commercial and industrial loan? A: The FDIC defines the category by what it leaves out: loans secured by real estate, loans to individuals, loans to depository institutions and foreign governments, loans to states and political subdivisions, and lease financing receivables.
Q: How much do US banks lend to businesses? A: FDIC-insured banks held $2.54 trillion in commercial and industrial loans on June 30, 2026, according to FDIC data. That excludes commercial real estate loans, which the FDIC reports separately.
Q: How concentrated is business lending among banks? A: Eight banks hold 50.6% of bank C&I loans, and the ten largest hold 54.7%, according to FDIC data for June 30, 2026.
Q: Why does a bank's rank change on US offices alone? A: The FDIC's C&I figure includes loans booked in a bank's offices abroad. Citibank books 56% of its C&I loans in foreign offices, so it places 7th on US offices rather than 4th, according to FDIC data.
Download the data
The 50 rows on this page (CSV), free. The full dataset has all 4,080 rows, as of June 30, 2026; we email you a link.
Frequently Asked Questions
Which US bank makes the most commercial and industrial loans?
Bank of America, with $323 billion in C&I loans on June 30, 2026, according to its Call Report filed with the FDIC.
What counts as a commercial and industrial loan?
The FDIC defines the category by what it leaves out: loans secured by real estate, loans to individuals, loans to depository institutions and foreign governments, loans to states and political subdivisions, and lease financing receivables.
How much do US banks lend to businesses?
FDIC-insured banks held $2.54 trillion in commercial and industrial loans on June 30, 2026, according to FDIC data. That excludes commercial real estate loans, which the FDIC reports separately.
How concentrated is business lending among banks?
Eight banks hold 50.6% of bank C&I loans, and the ten largest hold 54.7%, according to FDIC data for June 30, 2026.
Why does a bank's rank change on US offices alone?
The FDIC's C&I figure includes loans booked in a bank's offices abroad. Citibank books 56% of its C&I loans in foreign offices, so it places 7th on US offices rather than 4th, according to FDIC data.